Castro Valley Mental Health Claim Denial Lawyer
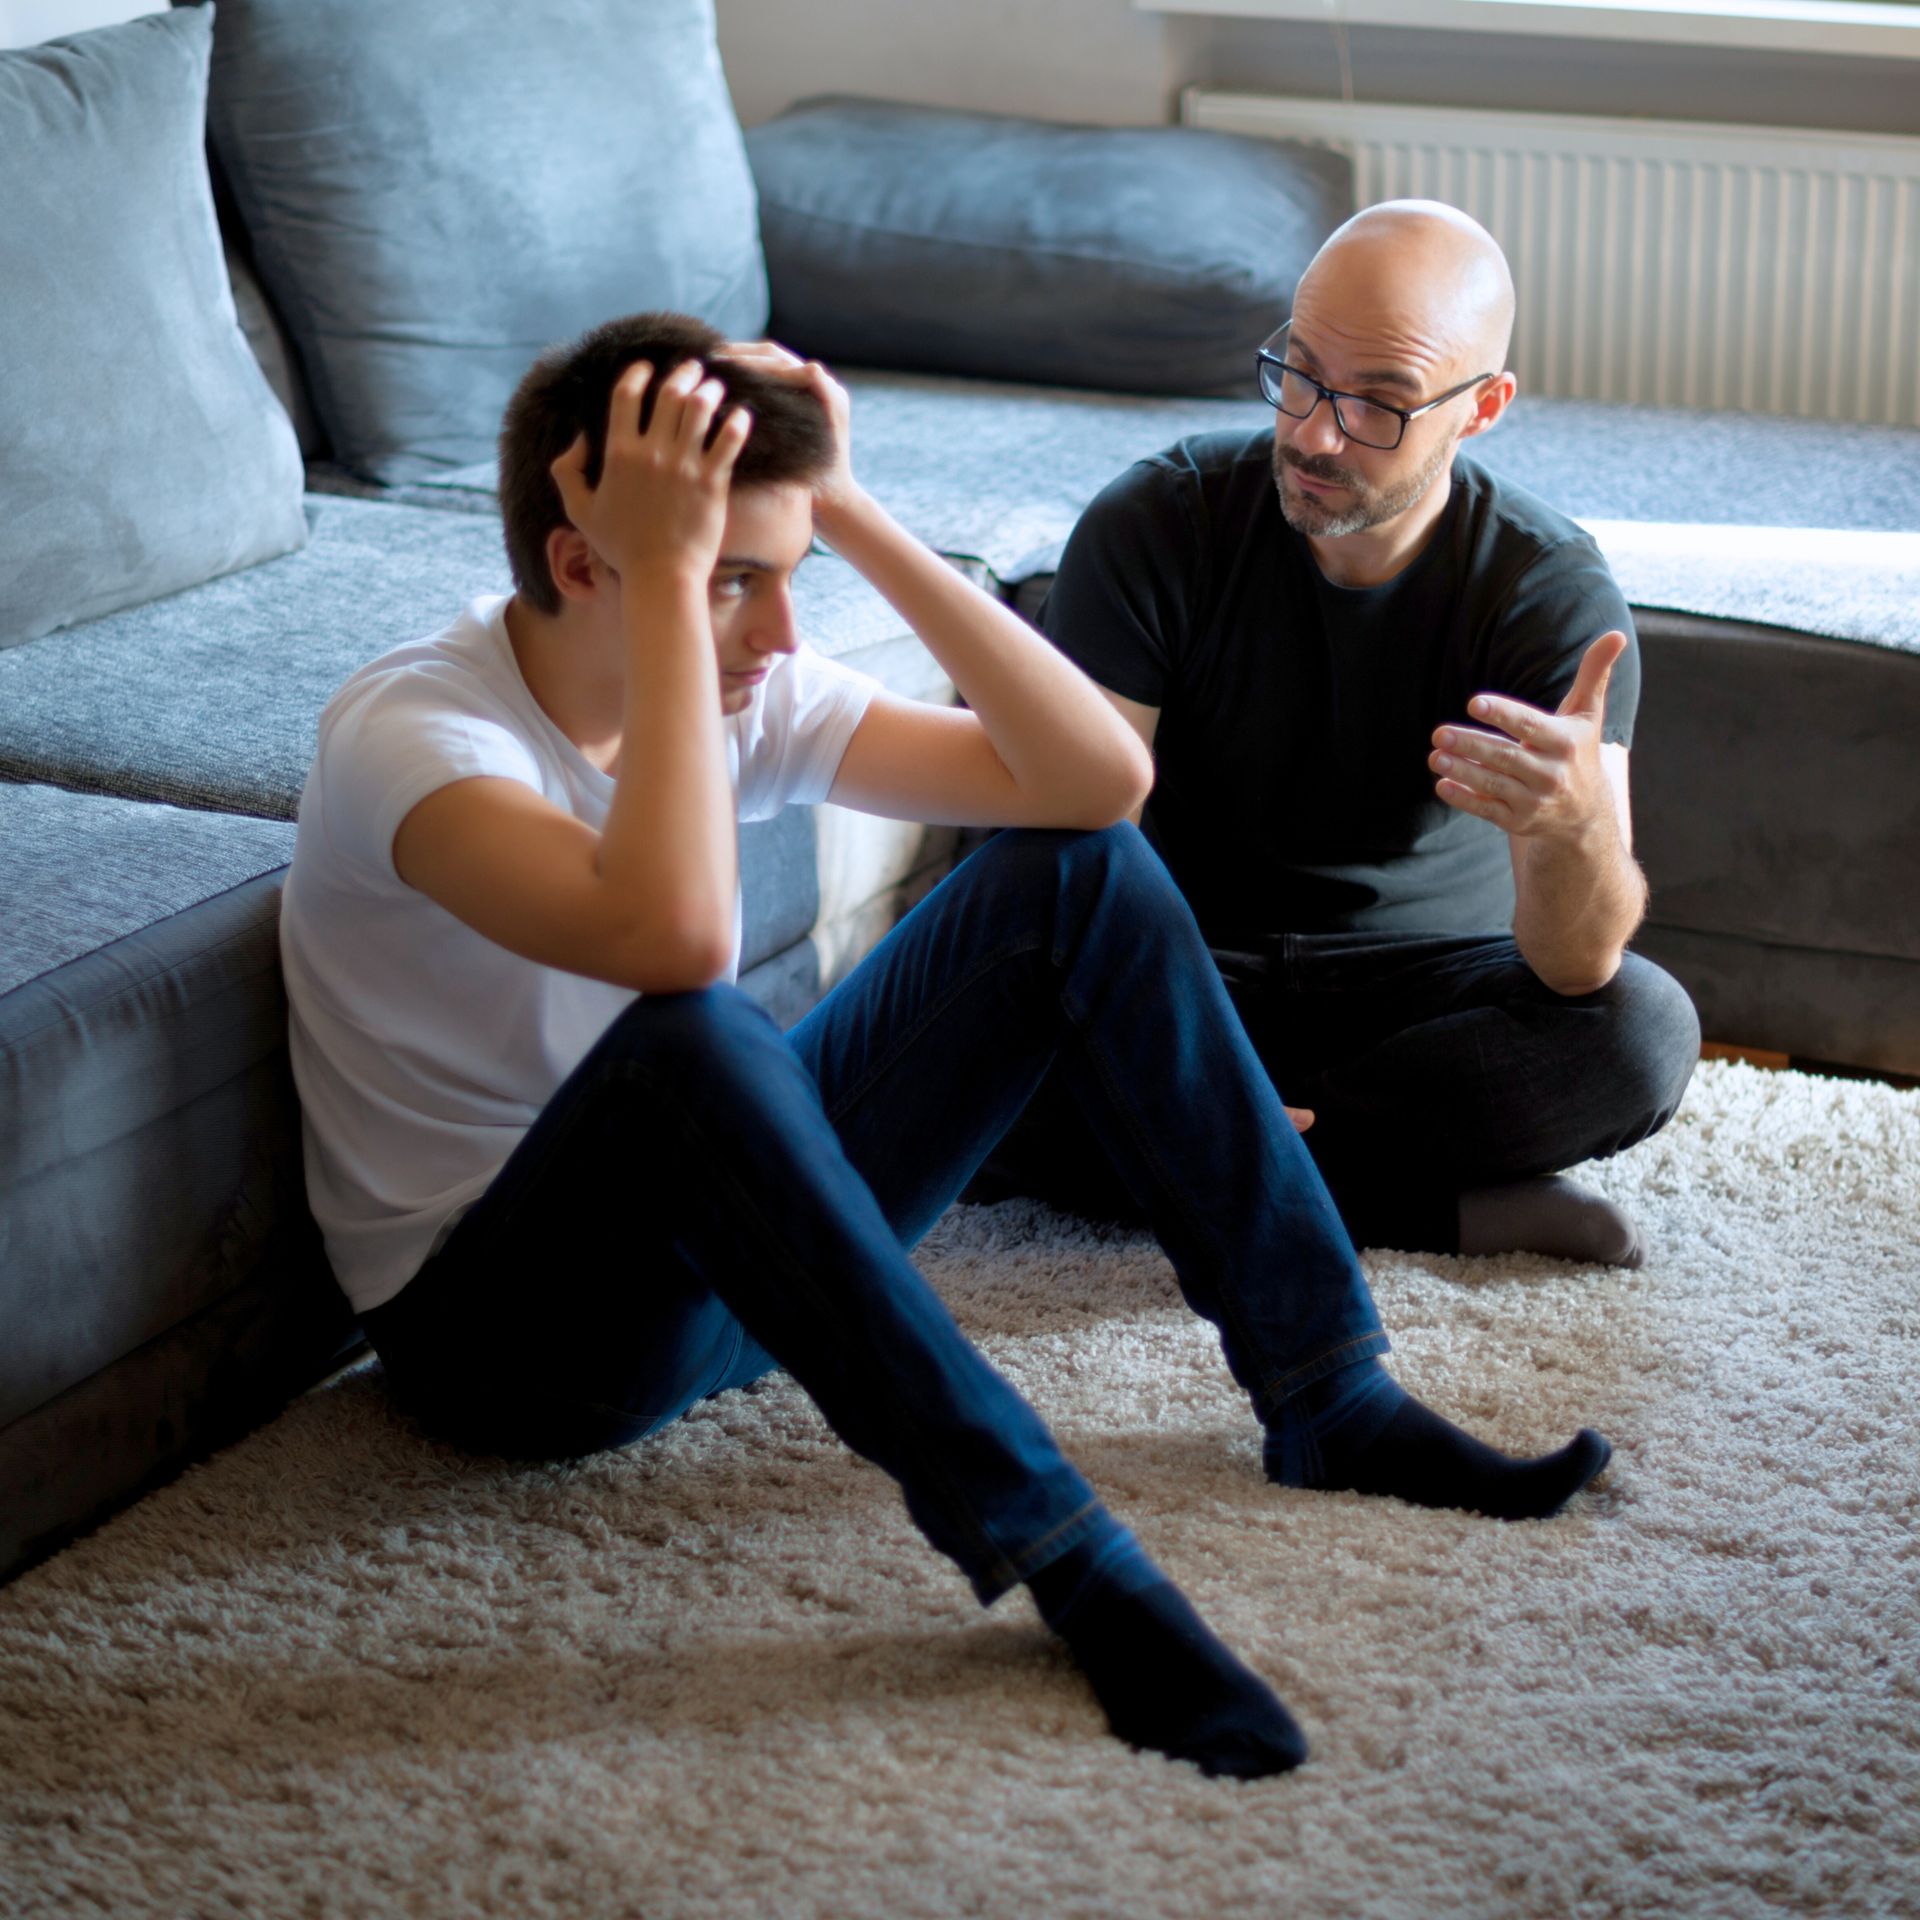
Getting access to mental health care can be an important part of protecting your health and well-being. When an insurance company denies a claim for mental health treatment, however, the financial and emotional consequences can be significant. A denial may leave you facing unexpected medical expenses or wondering how you will continue receiving recommended care.
If your health insurer has denied a mental health claim, you may have questions about why the claim was rejected and whether you can challenge the decision. At DL Law Group, we represent policyholders in insurance disputes, including matters involving denied health insurance benefits. Our attorneys help individuals understand their rights and navigate complicated disputes with insurance companies.
Our San Francisco law firm serves clients throughout the Bay Area, including Castro Valley. With 80 years of collective legal experience, our attorneys have extensive knowledge of insurance law and experience representing policyholders in disputes involving denied benefits, bad-faith insurance claims, and ERISA actions.
Mental Health Coverage and Insurance Disputes
Mental health treatment can take many forms. Depending on an individual’s circumstances and insurance plan, treatment may include outpatient therapy, psychiatric care, intensive outpatient services, partial hospitalization, residential treatment, or other forms of behavioral health care.
An insurance company may evaluate these services according to the terms and requirements of the applicable health plan. When a claim is denied, the reason given by the insurer can provide important information about the dispute.
A denial might involve questions about coverage, medical necessity, eligibility, authorization, documentation, or the level of care being requested. Understanding exactly why the insurer denied the claim is an important first step in determining how to respond.
Common Reasons for Mental Health Claim Denials
Insurance companies can deny mental health claims for different reasons. An insurer might state that a particular service is not covered under the plan or that the treatment does not meet the plan’s requirements.
In other situations, the insurer may contend that additional documentation is needed or that a particular level of treatment is not medically necessary under its criteria. A claim may also become disputed when the insurer and treating providers have different views about the appropriate type or duration of care.
The reason for the denial matters because the appropriate response can depend on the specific issue involved. Reviewing the denial together with the applicable policy or plan documents and supporting information can help clarify what is actually being disputed.
Challenging a Denied Mental Health Insurance Claim
Depending on the type of health insurance involved, there may be procedures for challenging a denied claim. These procedures can include an internal appeal or other form of review.
It is important to pay attention to the instructions and deadlines associated with the denial. The governing insurance policy or benefit plan may contain requirements concerning how and when a challenge must be submitted.
For some employer-sponsored health plans, ERISA may also affect the process. ERISA-covered benefit disputes can involve specific administrative procedures and legal considerations. If you believe your mental health claim was improperly denied, speaking with an attorney can help you understand the applicable process before you take your next step.
Mental Health Claims and Employer-Sponsored Plans
Many people receive health insurance through their employer. When a mental health claim is denied under an employer-sponsored plan, it may be necessary to determine whether the plan is governed by ERISA.
ERISA can affect how certain employee benefit claims are administered and challenged. It may also create specific procedures that a claimant must understand when disputing a benefit determination.
DL Law Group has experience representing policyholders in ERISA actions. If your mental health benefits are provided through an employer-sponsored plan, our attorneys can evaluate the circumstances and help you understand whether ERISA-related issues may affect your dispute.
Information to Gather After a Mental Health Denial
If your mental health insurance claim has been denied, preserve all documents related to the dispute. This can include the denial letter, explanation of benefits, insurance policy or plan documents, medical records, treatment recommendations, bills, and communications with the insurer.
Keep copies of emails, letters, and other correspondence. If you have spoken with insurance representatives by telephone, keeping notes about those conversations may also be helpful. You do not need to understand every document before contacting our office. Our attorneys can review the available information and help determine which details may be relevant to your dispute.
Frequently Asked Questions
Why would health insurance deny a mental health claim?
A mental health claim may be denied for different reasons, including disputes over coverage, medical necessity, authorization, eligibility, documentation, or the level of care. The specific reason should be identified in the insurer’s determination and reviewed against the applicable plan or policy.
Can I appeal a denied mental health claim?
Depending on your insurance plan, you may have an opportunity to appeal a denial or request another review. The applicable procedures and deadlines can vary, so it is important to carefully review the denial and governing plan documents.
What if my insurance company says treatment is not medically necessary?
Medical necessity disputes can involve the insurer’s interpretation of applicable criteria and the medical information supporting treatment. If you disagree with the determination, an attorney can review the circumstances and help you understand what options may be available.
Does ERISA apply to mental health insurance claims?
ERISA may apply to certain employer-sponsored health benefit plans. Whether it applies depends on the nature and structure of the plan. If your mental health benefits are provided through your employer, it may be important to determine whether ERISA governs your claim.
Should I hire a lawyer for a mental health insurance denial?
Not every denied claim requires legal representation. However, legal guidance may be valuable when a claim involves substantial expenses, repeated denials, complicated plan language, an employer-sponsored benefit plan, or concerns about how the insurer handled the claim.
Does DL Law Group offer free consultations?
Yes. DL Law Group offers free consultations. Contact our office to discuss your mental health insurance claim denial with our attorneys.
Contact DL Law Group Today
A mental health insurance claim denial can create uncertainty at a time when you may already be dealing with difficult personal circumstances. If you are in Castro Valley and your insurer has denied benefits for mental health treatment, understanding your rights can be an important first step.
At DL Law Group, we represent policyholders and individuals facing insurance disputes. Our attorneys bring 80 years of collective legal experience and substantial knowledge of insurance law to these matters. We understand the importance of carefully examining the policy, the claim history, the insurer’s decision, and the circumstances surrounding the requested treatment.
Our San Francisco-based firm serves clients throughout the Bay Area, including Castro Valley. We offer free consultations and are prepared to listen to your concerns, explain the issues involved, and help you understand the potential path forward. Contact DL Law Group today for a free consultation about your mental health insurance claim denial.
Case Review
Consultations are FREE! No fees unless we win your case.
Learn More
Why Choose DL Law Group?
At DL Law Group, we understand that when your insurance claim is wrongfully denied, it’s more than just a legal issue, it’s personal. Below are the key benefits we offer our clients because you deserve more than just representation. You deserve a legal team that listens, stands up to powerful insurance companies, and puts your needs first every step of the way.
We’ve built a strong reputation as experts in handling complex insurance bad faith cases and serving as trusted ERISA advocates. With a deep understanding of evolving insurance laws and years of focused experience, we deliver results that set us apart in the legal community.
Our clients often tell us we made a lasting difference in their lives. At DL Law Group, we combine legal excellence with genuine compassion. When we take your case, it’s because we believe in it. You can count on us to fight relentlessly for the justice you deserve.
We are well-respected throughout the legal and insurance communities. Judges, opposing counsel, and insurance carriers recognize our name and know we don’t back down.
We are aware of the tactics insurance companies employ to delay or deny valid claims. DL Law Group brings the legal firepower, experienced staff, and financial strength needed to level the playing field.